
Background: The Financial Conduct Authority has published the findings of a multi-firm review into how small and medium-sized businesses in the defence sector get on with their banks. It found the main problem was friction and delay, with long onboarding, repeated requests for information and slow decisions, rather than widespread refusal. The regulator introduced no new rules but told banks to judge each customer on its own risks.
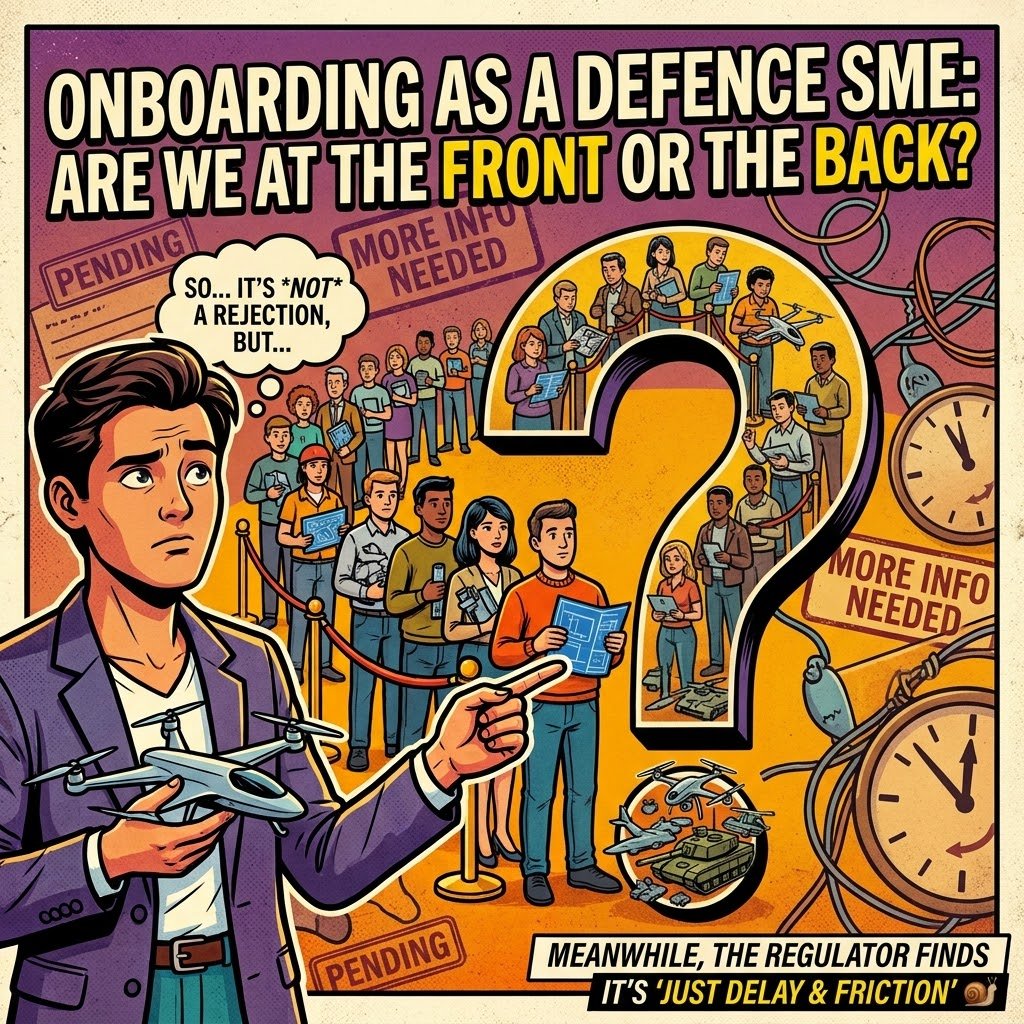
Ask anyone who has opened a business bank account lately and they will describe something between a job interview and a colonoscopy. Now try it while your company makes parts for drones.That, roughly, is the experience the Financial Conduct Authority set out to examine. Its review of how banks treat small defence suppliers was published on 26 October, and the conclusion is less dramatic than the industry gossip. The regulator did not find a wall. It found a queue.
Banks told the FCA they can and do take on defence customers, and some have built specialist teams to do it. Suppliers told it about onboarding that drags on for months, the same questions asked by three different departments, and decisions that appear to travel by carrier pigeon. The FCA summed it up as delay and friction rather than outright exclusion.
Why should a lawyer care? Start with what a bank is allowed to do. A business has no general legal right to a bank account. Banks can set their own appetite for risk and can say no. What they must do, under money laundering and sanctions law, is check who they are dealing with. The regulator’s point is that the checking should fit the customer actually standing in front of them.
The sector is huge and wildly mixed. A workshop machining brackets for armoured vehicles has little in common with a software house writing logistics code for the Ministry of Defence, and neither looks much like an arms dealer. Lumping them together is lazy, and the FCA says so, in the polite way regulators say most things.
The more revealing finding is about data. Many banks admitted they could not say how long their defence customers waited, whether decisions were consistent, or whether outcomes matched their own stated policy. That is a curious blind spot for an industry that can tell you to the penny what you spent on coffee last Tuesday. Without the numbers, nobody inside the bank notices that a lawful applicant has been sitting in a compliance in-tray since spring.
For compliance teams, the homework is fairly clear. Write down why a decision was made, who made it and which specific risk drove it. A file reading “sector: defence, declined” will not impress a supervisor or a complaints handler. Nor will a process so slow the customer simply gives up, which produces a refusal without anyone having to sign one.The FCA nudges suppliers too. Firms that can explain how they handle export controls and sanctions exposure, and hand over clear information early, tend to get through faster. Paperwork cuts both ways.
All of this sits against a government that wants a bigger domestic defence industry, and ministers have grumbled before about banks keeping their distance. The regulator has offered a cooler reading. The service exists. The plumbing is slow.Slow plumbing still floods the house. For a small supplier waiting on an account to pay staff or take a government contract, six months of delay does much the same damage as a flat no. It is just more polite about it.
Author: Thomas Greatbanks
Leave a Reply